
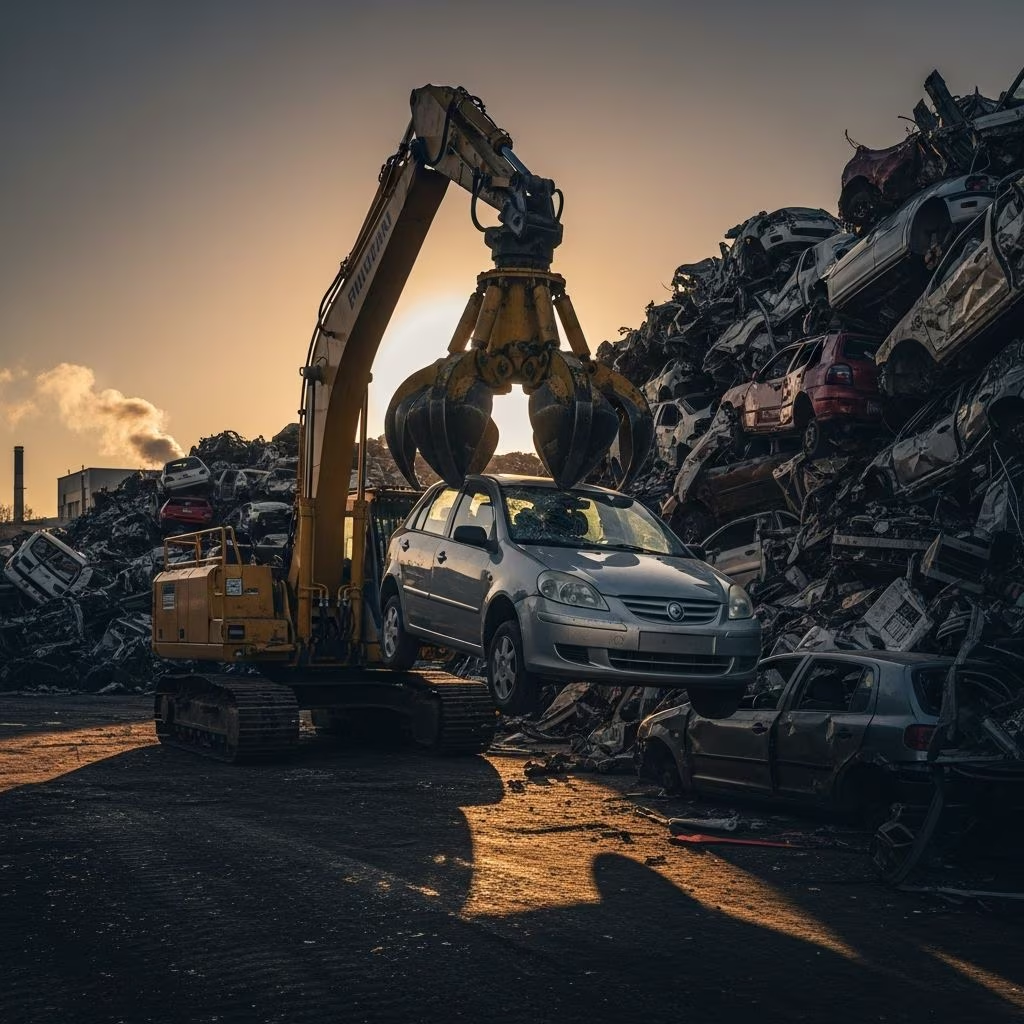
Across various regions, escalating car insurance premiums have reached unprecedented levels, compelling many vehicle owners to make the heartbreaking decision to scrap perfectly drivable cars simply because they can no longer afford coverage. This phenomenon reflects broader economic pressures, where the cost of maintaining a vehicle exceeds financial capacity for low- to middle-income households, leading to increased uninsured rates and heightened road safety risks.
The Surge in Premiums: A Nationwide Challenge
Car insurance rates have climbed sharply in recent years, driven by factors such as inflation, rising repair costs, and frequent claims. In Texas, for instance, average premiums have surged more than 50% since 2022, affecting low- to middle-income residents who are dropping coverage to cut expenses.Approximately 12% of Texas car owners now drive uninsured, with Harris County seeing over 14% of vehicles without insurance, according to a study by Texas Appleseed and United Way of Greater Houston.
Similar trends appear elsewhere. Colorado experienced a 20% increase in 2023 alone, with rates up 53% over the past decade, placing it among states with the highest premiums nationally. These hikes are not isolated; they stem from systemic issues like supply chain disruptions for parts and a rise in vehicle thefts, amplifying insurer payouts.
Why Owners Are Choosing to Scrap
When premiums become prohibitive, owners face a stark choice: pay up or part with their cars. Scrapping involves selling a vehicle for parts or metal, often for a fraction of its value, to avoid ongoing insurance mandates. This is particularly acute for older models, where high-risk profiles lead to exorbitant quotes.
- Financial Strain: Drivers with poor credit may pay 3 to 3.5 times more than those with excellent scores, exacerbating inequality.
- Regional Variations: Zip codes, gender, and coverage gaps further inflate costs, creating ‘unaffordable pricing’ for vulnerable groups.
- Legal Risks: Operating uninsured invites fines and penalties, pushing some to deregister and scrap vehicles preemptively.
Personal stories underscore the desperation. Many interviewed by advocacy groups express feeling ‘set up to fail,’ trapped by factors beyond their control like socioeconomic status.
Insurance Mechanics After Scrapping a Car
Scrapping alters insurance dynamics significantly. If a car is totaled in an accident, insurers typically purchase the salvage, factoring scrap value into payouts. Retaining a scrapped vehicle reduces compensation, as it excludes the junkyard resale amount.
Maintaining coverage during scrapping is advisable. Policies should remain active until the vehicle is officially dismantled to avoid coverage gaps, which could raise future rates. Most states mandate insurance on registered vehicles, even non-drivable ones, so cancellation post-scrapping prevents lapses.
| Scenario | Insurance Impact | Recommendation |
|---|---|---|
| Totaled in Accident | Insurer takes possession; payout includes scrap value | Surrender vehicle for full amount |
| Voluntary Scrapping | Remove from policy after scrapping | Keep active until title transfer |
| Retain Salvage | Lower payout; needs rebuilt title for future insurance | Avoid unless planning repairs |
Long-Term Affordability Trends and Data
Despite recent spikes, auto insurance has trended more affordable relative to income over two decades. From 2000 to 2022, premiums as a percentage of median household income declined, per the Insurance Research Council (IRC). However, affordability eroded from 2021-2024, projected to hit 1.7% of income in 2024—up from 1.4% in 2021 but below 2003’s 1.9% peak.
States like Florida illustrate reform potential. 2022-2023 laws curbed lawsuits, boosted insurer participation, and stabilized rates, offering a model for others.
Contributing Factors to the Crisis
Several elements fuel premium escalation:
- Inflationary Pressures: Higher costs for labor, parts, and medical claims directly pass to consumers.
- Social Pricing Models: Factors like credit history and location create disparities, with low-income areas hit hardest.
- Frequency of Claims: Increased accidents and thefts strain reserves, prompting rate adjustments.
- Regulatory Gaps: Inadequate oversight allows uneven pricing, as noted in Texas legislative pushes.
Experts like Ann Baddour from Texas Appleseed highlight how these dynamics disproportionately burden the working class, widening the gap between insured and uninsured drivers.
Consequences for Drivers and Society
The fallout extends beyond individuals. Uninsured drivers elevate risks for all road users, increasing accident costs absorbed by insured parties through higher premiums. In Texas, legislative leaders like Lt. Gov. Dan Patrick and Speaker Dustin Burrows are directing committees to probe protections and cost reductions.
Economically, scrapping functional cars wastes resources and limits mobility, critical for jobs and services in car-dependent areas. Low-income households suffer most, perpetuating poverty cycles.
Practical Strategies to Combat Rising Costs
Drivers aren’t powerless. Key tactics include:
- Shopping multiple quotes annually to leverage competition.
- Improving credit scores, as they heavily influence rates.
- Opting for higher deductibles or usage-based insurance (e.g., telematics devices).
- Bundling policies for home and auto discounts.
- Seeking state assistance programs or low-income subsidies where available.
Life adjustments, like safer driving or vehicle upgrades with safety features, can also mitigate hikes.
Government and Industry Responses
Responses are emerging. Texas lawmakers are tasked with enhancing oversight and affordability. Nationally, IRC studies urge balanced reforms to sustain long-term gains. Insurers must innovate, perhaps through AI-driven risk assessment, while regulators enforce fair pricing.
FAQs
What happens to my insurance when I scrap a car?
Keep the policy active until scrapping is complete to avoid gaps. Remove the vehicle afterward to prevent unnecessary premiums.
Why are insurance premiums rising so fast?
Factors include inflation, repair costs, claims frequency, and social rating variables like credit and location.
Is car insurance more affordable now than historically?
Relative to income, yes over 20 years, but recent years show declines in affordability.
Can I drive without insurance if premiums are too high?
No—it’s illegal and risks severe penalties. Consider alternatives like public transit temporarily.
How can I lower my car insurance costs?
Compare providers, bundle policies, improve credit, and choose safe vehicles.
Outlook: Toward Sustainable Solutions
The insurance crisis demands collaborative action. Reforms addressing root causes, coupled with consumer education, could restore balance. Until then, millions navigate tough choices, underscoring the need for equitable policies in an era of economic flux.
References
- Some owners are being forced to scrap cars because they can’t afford to insure them — Auto Express. 2023-10-01. https://www.autoexpress.co.uk/opinion/361408/some-owners-are-being-forced-scrap-cars-because-they-cant-afford-insure-them
- Soaring car insurance premiums force many low-to-middle income Texans to do without — Texas Public Radio (TPR). 2026-04-01. https://www.tpr.org/news/2026-04-01/soaring-car-insurance-premiums-force-many-low-to-middle-income-texans-to-do-without
- Colorado insurance costs are crushing vehicle owners — CBS Colorado (YouTube). 2024.
- How Does Scrapping a Car Affect Insurance? — Policygenius. 2024. https://www.policygenius.com/auto-insurance/how-does-scrapping-a-car-affect-insurance/
- Auto insurance affordability under scrutiny in new report — Insurance Business Magazine. 2024. https://www.insurancebusinessmag.com/us/news/auto-motor/auto-insurance-affordability-under-scrutiny-in-new-report-530172.aspx